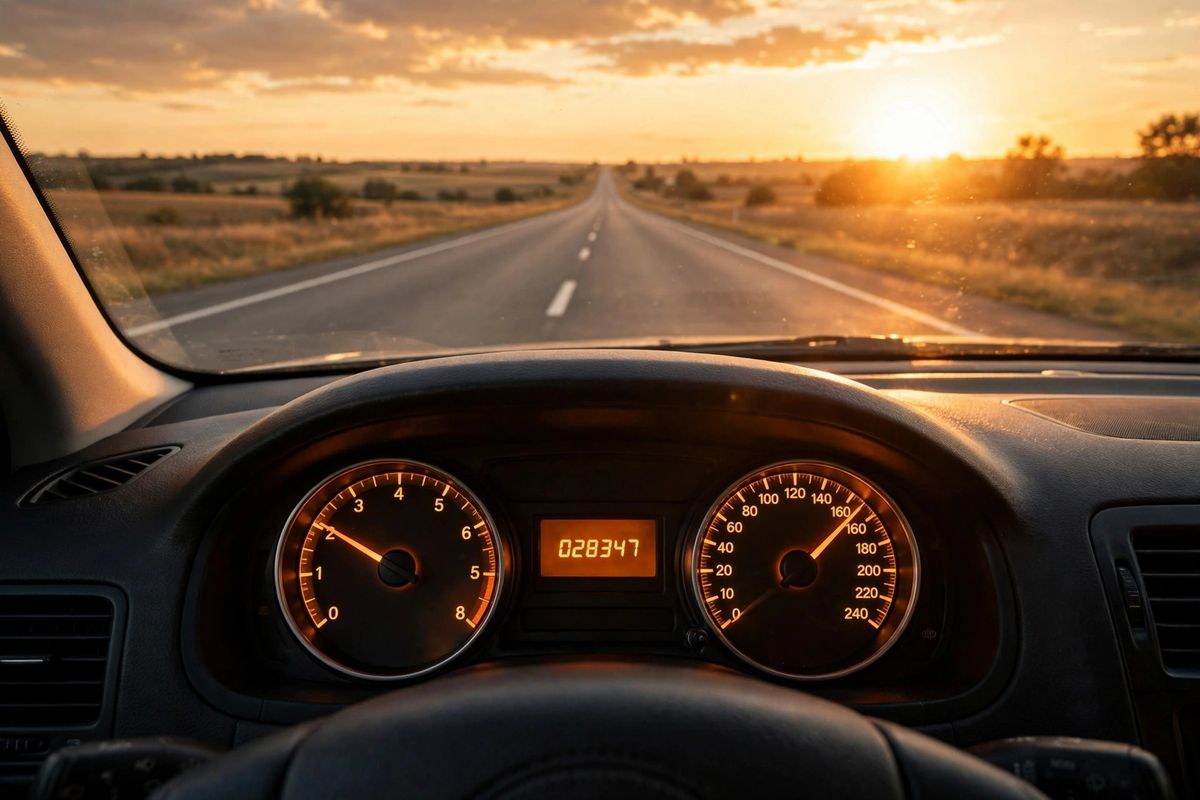
Every car lease comes with a mileage limit, and it is one of the terms that catches drivers off guard. You sign up for ten thousand miles a year, life happens, and suddenly the odometer is telling a different story than the contract. Understanding how annual mileage caps work before you sign is the difference between a lease that fits your life and one that punishes you for living it.
Mileage limits exist because a leased car’s future value depends heavily on how far it has been driven. The leasing company sets a residual value at the start, an estimate of what the car will be worth when you return it, and that estimate assumes a certain number of miles. Drive more, and the car is worth less than expected, which is why exceeding the cap triggers extra charges. Let us look at how these caps are structured, what they cost, and how to pick the right one.
How Annual Mileage Allowances Are Structured
Most leases offer mileage allowances in three standard tiers: ten thousand, twelve thousand, or fifteen thousand miles per year. These are annual figures, but they are enforced over the full term of the lease. On a three year lease at twelve thousand miles per year, your total allowance is thirty six thousand miles, and what matters at the end is the odometer reading, not how the miles were distributed across individual years.
That total allowance structure gives you some breathing room. If you drive fourteen thousand miles in year one and ten thousand in year two, you are still on track for a thirty six thousand mile total. The leasing company does not penalize you for a heavy year as long as the final number lands within the cap. This flexibility is worth remembering when you are estimating, because most people’s driving is not perfectly even from year to year.
What Exceeding the Cap Costs You
Go over your total allowance, and you will pay an excess mileage charge, typically between fifteen and thirty cents per mile. That rate is set in your lease contract at signing, so there are no surprises if you read the paperwork. On a car driven five thousand miles over the limit at twenty five cents per mile, the bill comes to one thousand two hundred fifty dollars, due when you return the vehicle.
Excess mileage fees are one of the most common sources of lease end sticker shock, right alongside charges for wear and tear beyond normal standards. Both are assessed at turn in, and both are avoidable with planning. The per mile rate sounds small in isolation, but miles accumulate quietly, and a long commute change or a few road trips can push you thousands of miles past the cap before you notice.
Choosing the Right Mileage Tier Before You Sign
The best time to think about mileage is before the lease starts, when you can buy extra miles at a discount. Most leasing companies let you purchase additional miles upfront at a lower per mile rate than the end of lease penalty. If you know you drive fourteen thousand miles a year, stepping up from the twelve thousand tier to the fifteen thousand tier at signing is almost always cheaper than paying overage fees later.
To estimate honestly, look at your actual driving history rather than your optimistic guess. Check your current car’s odometer and service records, or think through your weekly routine: commuting miles, school runs, weekend trips, and the occasional long drive to visit family. Then add a buffer of ten to fifteen percent for the unexpected. People consistently underestimate their driving, and the cost of overestimating slightly is far less than the cost of blowing past the cap.
When the Lowest Tier Makes Sense
The ten thousand mile tier suits drivers with short commutes, a second vehicle for long trips, or a work from home routine. If your daily driving is minimal and you fly rather than drive for vacations, this tier keeps your payments lowest. Just be realistic. If your life changes mid lease and you start commuting, you cannot retroactively switch tiers for free.
When to Step Up to Fifteen Thousand
Long commuters, sales professionals, and anyone who regularly drives between cities should take the fifteen thousand mile tier without hesitation. The payment increase is modest compared to the overage bill you would otherwise face. As a rough guide, if you drive more than about twelve hundred miles a month, the top tier is your safest choice.
Can You Buy Extra Miles During the Lease
Many leasing companies allow you to purchase additional miles mid lease, often at a rate between the upfront discounted price and the end of lease penalty. This is a useful safety valve if your driving patterns change. A new job with a longer commute, a move to the suburbs, or a lifestyle shift can all push your mileage up, and buying miles midway is far better than hoping the overage goes unnoticed.
Not every lessor offers mid lease mileage purchases, and the price varies, so check your contract or call the leasing company to ask. If the option exists, the earlier you buy, the better the rate tends to be. Waiting until the final month usually means paying the full penalty rate, so monitor your odometer against your prorated allowance at least once or twice a year.
How Mileage Affects Your Monthly Payment
Higher mileage allowances raise your monthly payment, and the mechanism is straightforward. A car expected to have forty five thousand miles at lease end is worth less than the same car with thirty thousand miles, so the residual value drops. A lower residual means a bigger gap between the car’s price and its end value, and you pay that gap through your monthly bills.
The increase is usually reasonable. Moving from twelve thousand to fifteen thousand miles per year might add twenty to forty dollars a month on a typical lease. Compare that to paying twenty five cents per mile on nine thousand excess miles, which is two thousand two hundred fifty dollars at turn in. The math clearly favors buying the miles upfront when you know you will need them.
Mileage and Your End of Lease Options
Your mileage situation shapes what makes sense at lease end. If you stayed well under the cap, the car may be worth more than the residual value stated in your contract, which can create an opportunity. You might buy the car and keep a vehicle with low miles, or trade it in and capture some of that extra value toward your next lease.
If you went over the cap, returning the car and paying the overage is the straightforward path, but it is not your only one. Buying the car at the residual price avoids the mileage penalty entirely, since overage charges apply only when you hand the car back. Depending on the car’s market value, that can be the cheaper move. And if you need to get out of the lease before it ends, remember that high mileage makes a lease transfer harder to sell, since the next driver inherits the remaining allowance.
Tracking Your Miles Throughout the Lease
The simplest habit that prevents mileage surprises is a quick odometer check against your prorated allowance. Divide your total mileage allowance by the number of months in the lease to get your monthly pace, then compare it to your actual odometer every few months. If you are running hot, you have time to adjust, buy miles, or plan for the buyout option.
Many drivers find it helps to note the odometer reading at each oil change or tire rotation, creating a natural record without extra effort. Some leasing companies also show your mileage pace in their online account portals. Whatever method you use, the goal is the same: no surprises at turn in. A lease works best when the end of the term is a calm handover, not a scramble to explain ten thousand extra miles.
The Bottom Line on Mileage Caps
Annual mileage caps are not a trap, but they do reward honest planning. Estimate your driving generously, buy the tier you will actually need, and check your pace a couple of times a year. The per mile penalty is entirely avoidable, and the peace of mind that comes from knowing your driving fits the contract is worth the small upfront cost of the right tier. Choose the cap that matches your real life, and the odometer becomes one less thing to worry about.