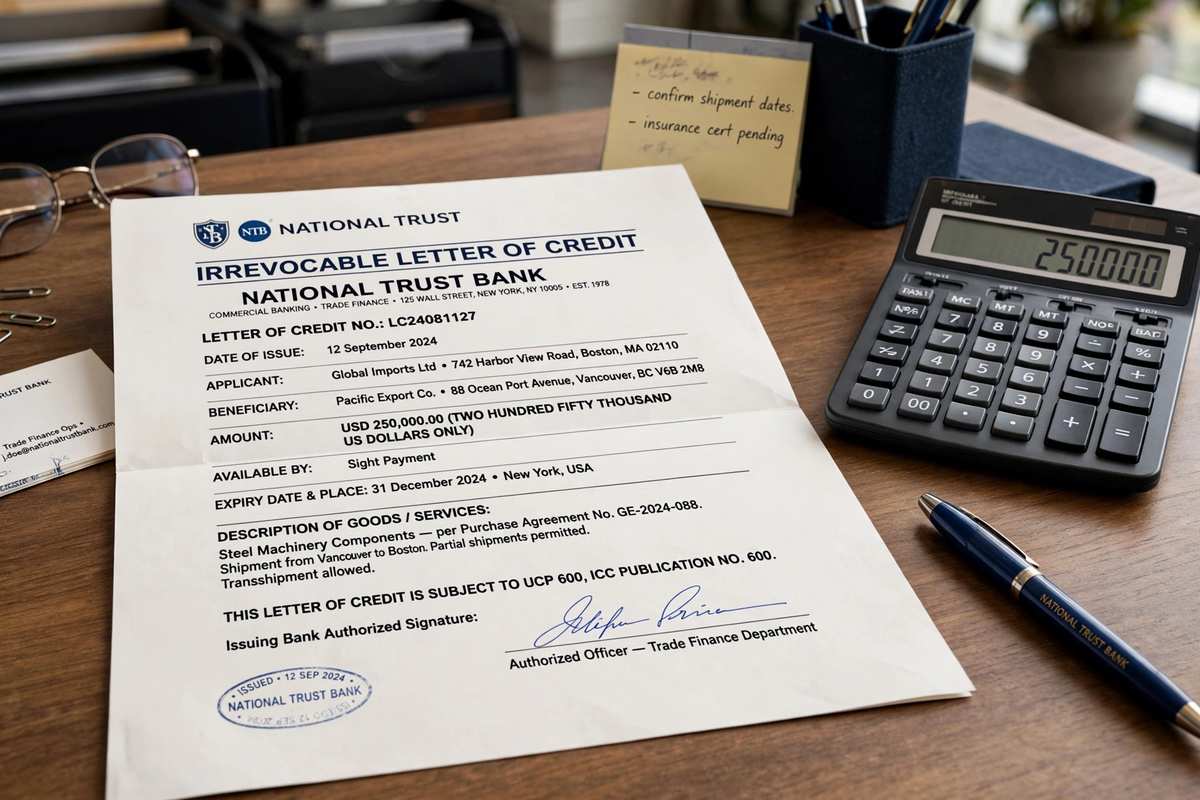
When a landlord wants extra assurance that rent will be paid, two instruments often come up: a lease guaranty and a surety bond. Both give the landlord someone to turn to if the tenant defaults. They work very differently, cost different amounts, and create different risks. Choosing the wrong one can cost you money, flexibility, or both.
The confusion is understandable. Both involve a third party promising to cover the tenant’s obligations. Both are called security. But a guaranty is a personal promise, usually from a business owner or parent company, while a surety bond is a commercial product sold by a bonding company for a premium. The legal mechanics, the underwriting, and the consequences of a claim diverge sharply from there.
What a Lease Guaranty Is
A lease guaranty is a contract in which a third party, the guarantor, promises the landlord that the tenant’s lease obligations will be fulfilled. If the tenant fails to pay rent or otherwise defaults, the landlord can demand payment directly from the guarantor. The guarantor is typically a business principal, a parent corporation, or another party with assets the landlord trusts.
Guaranties come in two flavors. A payment guaranty makes the guarantor liable the moment the tenant misses a payment, with no need for the landlord to sue the tenant first. A collection guaranty requires the landlord to exhaust remedies against the tenant before turning to the guarantor. Most landlord drafted guaranties are payment guaranties, which is faster for the landlord and harsher for the guarantor.
The cost of a guaranty
A guaranty costs nothing upfront. Nobody pays a premium or a fee to sign one. The cost is entirely in the risk: the guarantor’s personal or corporate assets are on the line for the full lease obligation. For a business owner, that can mean the house and the savings account. The absence of an upfront price tag makes guaranties deceptively easy to sign.
What a Surety Bond Is
A surety bond is a three party agreement involving the tenant as principal, the landlord as obligee, and a surety company that issues the bond. The surety promises the landlord that it will pay if the tenant defaults, up to the bond amount. In exchange, the tenant pays the surety an annual premium, typically a percentage of the bond amount based on the tenant’s creditworthiness.
Unlike a guaranty, a surety bond is a regulated financial product. The surety company underwrites the tenant much like an insurer underwrites a policyholder, examining financials, credit history, and business experience. If the tenant’s credit is weak, the premium rises or the bond may be unavailable. This underwriting is both a hurdle and a benefit: it forces an honest assessment of whether the tenant can actually afford the lease.
The cost of a bond
Surety bond premiums for lease bonds typically run from one to five percent of the bond amount per year, depending on the tenant’s financial strength. A one hundred thousand dollar bond might cost one to five thousand dollars annually. That is real money every year, but it buys something a guaranty does not: the tenant’s personal assets stay out of the picture unless the surety pursues indemnification, which standard bond indemnity agreements do allow.
Key Differences at a Glance
The practical differences between the two instruments show up in five areas that matter to tenants.
Who pays upfront
A guaranty has no upfront cost beyond legal fees to review it. A surety bond requires annual premiums for the life of the bond. Over a long lease, premiums can add up to a significant fraction of the bond amount.
Whose assets are at risk
A guaranty puts the guarantor’s personal or corporate assets directly on the line. A surety bond puts the surety company’s capital on the line first, though the tenant typically signs an indemnity agreement promising to reimburse the surety for any claims paid. Read that indemnity agreement carefully. It can recreate much of the personal exposure the bond seemed to avoid.
How claims get paid
Under a payment guaranty, the landlord demands money from the guarantor and the guarantor pays or gets sued. Under a surety bond, the landlord files a claim with the surety, which investigates before paying. The investigation step gives the tenant a buffer that a guaranty does not provide. It also means the landlord may prefer the guaranty for its speed.
Underwriting and availability
Anyone with assets can sign a guaranty. A surety bond requires passing the surety’s underwriting, which screens out tenants the surety considers too risky. Paradoxically, the tenants who most want to avoid a personal guaranty are often the ones who cannot qualify for a bond.
Effect on relationships
A guaranty is personal. It often strains the relationship between business partners or between a parent company and a subsidiary when things go wrong. A surety bond is commercial and impersonal. The tenant pays a premium, the surety takes the risk, and nobody’s Thanksgiving dinner is ruined.
Which One Landlords Prefer
Most landlords prefer a guaranty, and the reasons are straightforward. A guaranty is faster to enforce, has no annual renewal risk, and gives the landlord direct access to a real person’s assets. A surety bond introduces a claims process, an annual renewal the tenant might let lapse, and a corporate surety with lawyers of its own.
Landlords also know that a personal guaranty aligns incentives. A business owner who has guaranteed the lease personally will move mountains to keep the rent current. A tenant who merely pays a bond premium has less skin in the game. That behavioral difference is worth a lot to a landlord choosing between the two.
Which One Tenants Should Prefer
Tenants usually prefer the surety bond, for equally straightforward reasons. The bond keeps personal assets out of direct reach, converts an unlimited risk into a known annual cost, and avoids entangling personal relationships in business obligations. For a tenant choosing between a personal guaranty and a bond, the bond is often the rational choice if the premiums are affordable.
Tenants should also consider the hybrid approach. Offer a limited guaranty with negotiated caps, which gives the landlord the direct enforcement it wants while keeping the tenant’s exposure defined. Many landlords will accept a capped guaranty more readily than a surety bond, making it the practical compromise.
Negotiating Tips for Either Instrument
Whichever instrument you use, several negotiation points apply to both. First, define the trigger precisely. The landlord should have to show a specific monetary default, not just allege a general breach, before demanding payment. Vague triggers invite opportunistic claims.
Second, require notice and a cure period. The tenant should get written notice of the claimed default and a reasonable time to cure before the landlord turns to the guarantor or the surety. This basic fairness protection is sometimes missing from landlord drafts.
Third, address what happens after a claim. Under a guaranty, does the guarantor get the tenant’s rights against the landlord, such as the right to cure and continue the lease? Under a bond, does the tenant have to replenish or replace the bond after a draw? Spell out the post claim mechanics in the lease rather than discovering them in a crisis.
Fourth, coordinate with the security deposit provisions. The lease should say whether the landlord must apply the deposit before calling the guaranty or the bond. Without that sequencing, a landlord could double recover, taking the deposit and the full guaranty amount for the same default.
Common Mistakes to Avoid
The most common mistake is signing a guaranty without reading the waiver section. Landlord drafted guaranties routinely waive the guarantor’s rights to notice of default, to require the landlord to pursue the tenant first, and to approve lease amendments. Each waiver removes a protection you would otherwise have. Strike them or narrow them wherever possible.
With surety bonds, the most common mistake is ignoring the indemnity agreement. Tenants focus on the bond premium and overlook the separate agreement in which they promise to reimburse the surety for claims, plus the surety’s legal costs. That indemnity can reach the same personal assets the bond was supposed to shield. Have your attorney review the indemnity agreement with the same care as the bond itself, and tie the duration of either instrument to the duration of the obligation it secures, in writing. The same discipline applies to upfront deposits held as security, where tenants should confirm exactly when and how the money comes back.
The Bottom Line
A lease guaranty is free to sign and potentially devastating to honor. A surety bond costs money every year but keeps the risk commercial and contained. Landlords prefer guaranties for their speed and bite. Tenants prefer bonds for their boundaries and predictability. Whichever you choose, negotiate the trigger, the notice, the sequencing with the deposit, and the duration. The instrument only matters when the tenant defaults, which is exactly when you will be glad the paperwork was precise.